Once, Nike was one of the strongest brands globally and a stock investors believed would sustain long-term growth. It had a global-scale business, a massive customer base, powerful marketing, a network of world-class athletes, and the ability to build brand identity and set trends. Nike shoes became more than sports products; they became part of the culture and lifestyle of consumers worldwide.
But today, that image is changing...
Nike's stock price has dropped about 78% from its 2021 peak of $167.31 per share to approximately $38 per share. The company's market value has declined by more than $220 billion, equivalent to over 7 trillion baht, compared to its highest valuation.
Recently, Nike faced a symbolic blow when it was removed from the S&P 100, an index of major U.S. Blue Chip companies. S&P Dow Jones Indices announced the change would take effect before the market opened on 21 Sep 2026 GMT+7, after Nike's nearly 18-year presence in the index.
What exactly happened to the brand that once set the rules in the sports industry?
Nike's stock decline is not due to a single factor but the accumulation of multiple issues over recent years, including sales channel strategy, reliance on legacy franchises, new competitors, challenges in the Chinese market, and supply chain costs. Many of these problems are interconnected more than they appear.
A key turning point was Nike's accelerated expansion of Direct-to-Consumer (DTC) business during the COVID-19 pandemic. Nike invested heavily in its own channels—website, Nike app, and SNKRS—while reducing dependence on wholesale retailers and partners.
This strategy made sense as consumers increasingly bought online, allowing Nike to control customer experience, collect data, and manage pricing independently. However, as the world reopened, consumer behavior shifted back to physical stores where customers want to see and try products, especially shoes where fit, comfort, and use significantly influence purchase decisions.
At the same time, relationships with major retail partners like Foot Locker, Dick’s Sporting Goods, and JD Sports suffered. Nike then needed years to rebuild these retail partnerships. The issue wasn’t just poor online sales, but Nike restructuring its sales channels while competitors gained shelf space and built real-world consumer connections.
Shelf space once dominated by Nike started to be shared with other brands.
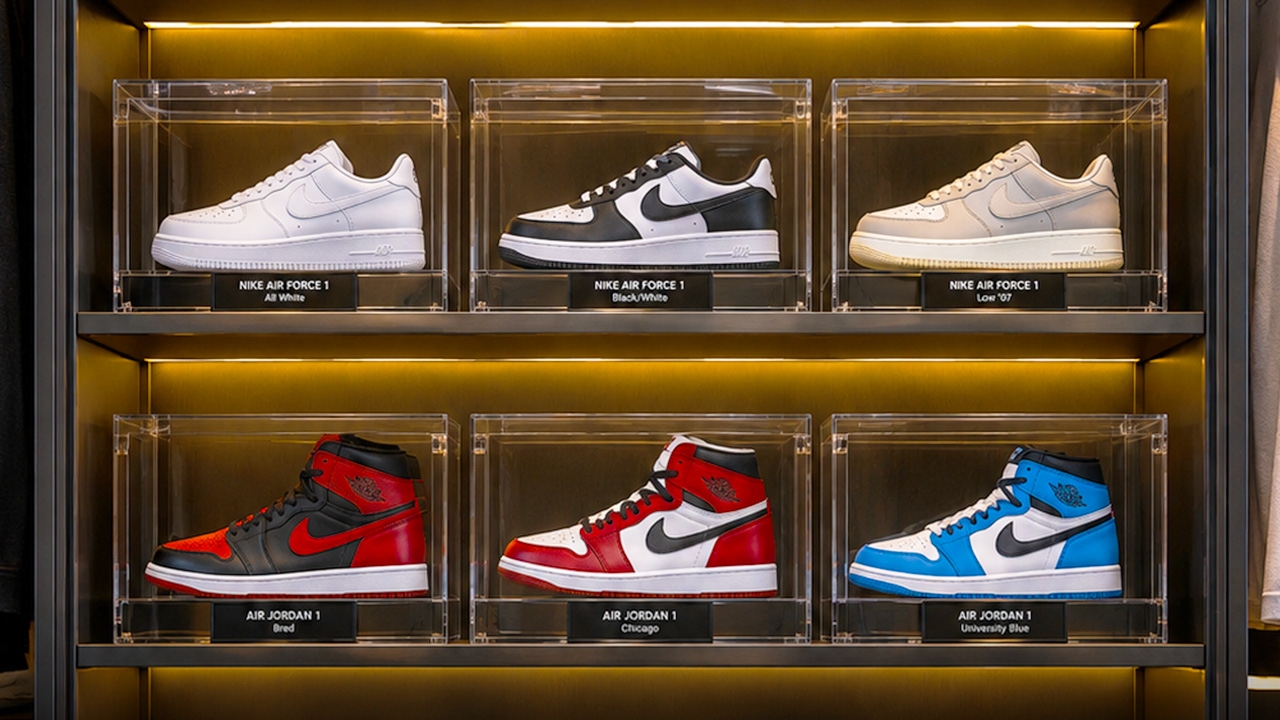
Another critical challenge was Nike's heavy dependence on historically successful shoes and franchises like Air Force 1, Dunk, Air Jordan, and various Retro models for too long. These franchises remain valuable assets and generate significant sales, but overreliance turned a strength into a limitation.
Consumers may no longer want to see the same models repeatedly reissued in new colors or styles, while sneaker trends shift from classic sneaker culture toward performance and running shoes emphasizing technology, comfort, and function. This shift has enabled new competitors to disrupt the market.
The growth of brands like Hoka, On, Brooks, Saucony, and New Balance shows that competition in the sports shoe market is no longer just about brand fame. Today’s consumers focus more on running shoes and footwear with advanced technology.
Nike grew by creating brand desire—one shoe could become a trend, and wearing Nike made consumers feel part of a culture. Many newer brands grow by creating product desire that genuinely meets the needs of newer consumer segments.
Simply put, in the past people bought Nike to wear Nike, but today some consumers choose Hoka for cushioning and shock absorption, On for unique design and technology, or other brands because their products better solve specific pain points. As purchase motivations change, brand strength alone may no longer suffice.
These factors have intensified Nike’s competition in technology, design, brand image, and market share, especially in the running shoe segment, a key market for Nike, with declining market share results.
According to GlobalData, Nike’s global sportswear market share fell from 15.2% in 2023 to 14.1% in 2024, while Adidas, New Balance, On, and Hoka gained share. The running shoe market, once a stronghold for Nike, has become fiercely competitive.
Another significant pressure point for Nike is challenges in China, once a key growth market. Nike now faces weaker purchasing power and rising competition from strong local brands like ANTA and Li-Ning, which excel in quality and brand image.
The “Guochao” trend—meaning a nationalist wave valuing Chinese brands, products, and culture—especially during COVID-19, accelerated this shift. Meanwhile, Chinese brands continuously improve products and technology, causing Nike to lose brand preference and making its global brand strength less effective than before.
Nike also faces cost pressures due to most products being manufactured abroad, subject to U.S. import tariffs, especially after the Trump administration’s tariff measures took effect in 2025.
Nike had to raise prices on some products to offset increased costs, but with more consumer choices, price hikes risk driving customers away if they don’t perceive sufficient differentiation. Thus, cost pressures impact not only company margins but also brand competitiveness.
Nike once epitomized an ideal Consumer Growth stock, with global scale, a strong brand, cultural popularity, vast distribution networks, pricing power, and international growth.
Many investors believed Nike could sustain growth returns for a long time. But as the business faltered, these beliefs were challenged one by one. Growth investors had less reason to hold as growth slowed, momentum investors exited as share price lost momentum, and quality investors reconsidered the company’s competitive moat.
As beliefs shifted, so did the stock price, plunging nearly 80% from over $167 in 2021 to about $38 today, wiping out more than $220 billion in market value.
Amid these challenges, Nike appointed Elliott Hill, a veteran executive with over 30 years at the company, as CEO in October 2024 to lead the turnaround. He aims to address multiple issues simultaneously, including restoring wholesale partner relations, refocusing on sports products, managing distribution, and driving new product launches.
However, Nike’s turnaround cannot rely on strategy changes alone. Ultimately, success depends on customer return, sales of new products, and crucially, whether Nike can stop losing market share to competitors.
Market sentiment toward Nike has evolved with its business situation. Since July, signs of a potential recovery emerged as Elliott Hill began tackling longstanding problems.
Nike started rebuilding retailer partnerships, refocused on sports, resolved distribution issues, and pushed new products to regain consumer interest. However, stock prices still reflected high expectations for the recovery, requiring investors to bet on the speed of Nike’s return to growth.
By August, concerns resurfaced due to Nike’s weakening competitive position, declining shoe market share, ongoing challenges in China, and rising competitors like Hoka and On. Advantages once seen as strong barriers now appear less durable.
Nike’s removal from the S&P 100 may carry more sentimental than direct business impact. The company remains in the S&P 500 and retains its status as a major U.S. company. Nonetheless, this event highlights how far Nike has fallen from investors’ previous expectations, now needing to prove whether its competitive advantages can still drive growth.
This may be Nike’s toughest challenge: strong brand recognition does not guarantee consumer purchases, nor does a large distribution network ensure sales if products no longer create demand.
Ultimately, Nike must prove more than stock price recovery or launching multiple new products. The brand must demonstrate it can lead the sports world and shape the market’s future. If Nike merely follows the running trend with recent products like Vomero boosting sales, it risks being a follower rather than a leader. In a market with more choices, being the biggest brand may no longer suffice.
True turnaround is measured not just by stock price but by consumer behavior, market share, new products that generate real demand, and the brand’s ability to create new trends.
Nike still has the resources and brand capital to recover, but no one can guarantee its ability to reclaim leadership in a changed competitive landscape. Ultimately, Nike may not be fighting to return to its 2021 form but to define the "next version" of Nike.
Source of information Yahoo Finance , Forbes
Click to read the BrandStory column More Read business news, marketing strategies, and exclusive interviews with ThairathMoney to help you "Better Finance, Better Life" at
https://www.thairath.co.th/money/business_marketing Follow Facebook page: Thairath Money at this link https://