Throughout the past year, Stablecoins have shifted from being assets primarily known through the crypto world to a technology closely watched by the global financial sector as a new infrastructure. This comes amid opportunities to improve payment efficiency and cross-border money transfers, alongside critical challenges related to regulation, financial stability risks, and the role of central banks that must be considered concurrently.
This issue is thus a key dimension of discussions at the IMF-World Bank Group Annual Meetings 2026 in Bangkok. This forum brings together economic leaders, policymakers, and financial sectors worldwide to exchange views on global economic directions, including the future of financial systems and technologies that will transform money movement in the years ahead.
For Thailand, this is a pivotal moment to determine how Stablecoins will play a role and evolve from digital asset trading markets into infrastructure supporting tourism, trade, investment, and cross-border transactions, while maintaining financial system stability.
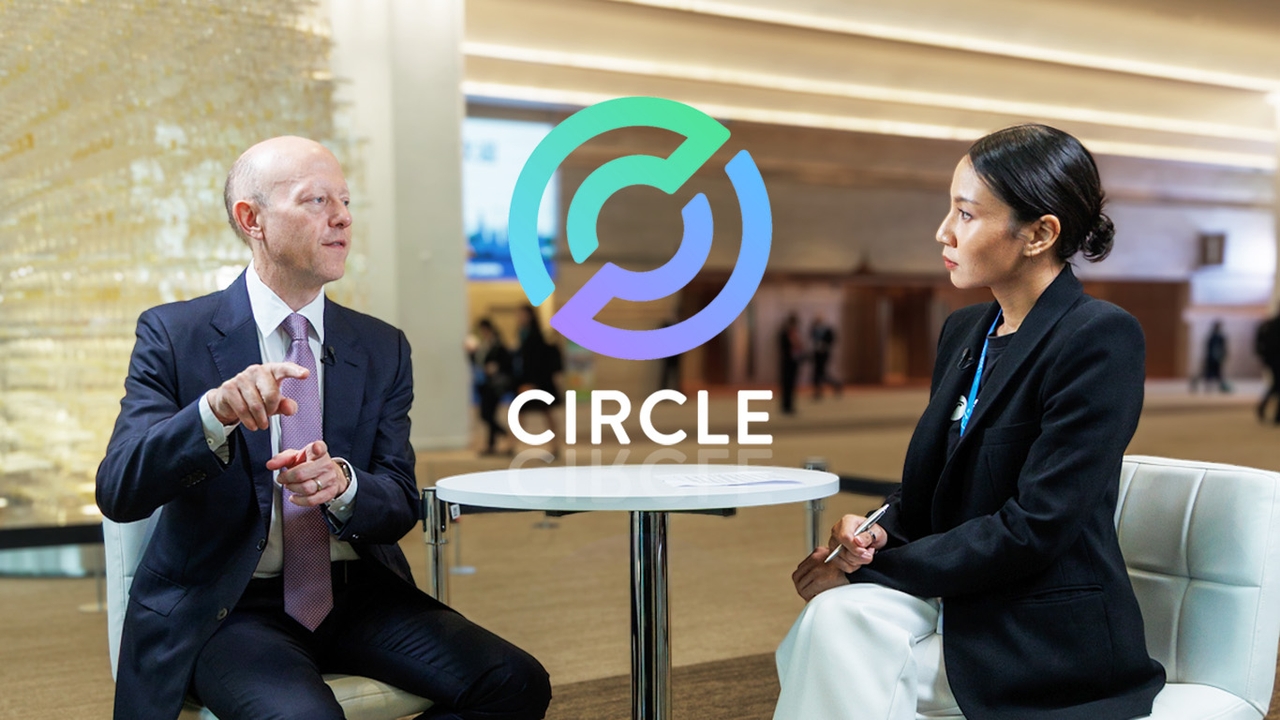
On this occasion, Thairath Money spoke with Jeremy Allaire, co-founder and CEO of Circle, the company behind USDC, one of the most influential Stablecoins globally, to explore the direction of the Stablecoin Economy—from opportunities of the THAI BAHT Stablecoin, regulatory conditions, dialogues with the Bank of Thailand, to potential collaborations with Thailand's business sector.
From the perspective of a global digital financial infrastructure builder, where does Thailand's Stablecoin industry currently stand, and what steps are needed to transform technological trends into practical applications within the economy?
For Thais who may be unfamiliar with Circle or unclear about what Stablecoins are,
Stablecoins are digital assets designed to maintain relatively stable values, often pegged to reference assets such as the US dollar. This contrasts with cryptocurrencies like Bitcoin, which can experience significant price volatility.
The primary purpose of Stablecoins is to allow users to hold and transfer digital value without facing the same level of price fluctuation typical of general cryptocurrencies. Their value stability depends on mechanisms to preserve value, backing assets, and the issuer's credibility.
Simply put, Stablecoins are like digital US dollars, similar to holding a one-dollar bill but converted from physical cash in your wallet to a digital token transferable on a blockchain system.
One of the well-known Stablecoins globally is USDC, issued by Circle and designed to maintain a value pegged to the US dollar at a 1:1 ratio. What makes USDC particularly notable is that Circle, the technology company behind it, positions itself not just as a Stablecoin issuer but as a developer of infrastructure connecting digital money with broader payment and financial systems.
Recently, Circle became the first company to obtain a digital banking license in the United States, after receiving final approval from the Office of the Comptroller of the Currency (OCC), the federal banking regulator, to establish National Trust Bank, under the name Circle National Trust in July 2026, providing asset custody services to institutional clients under federal supervision.

Jeremy stated that Circle is an internet software and infrastructure company enabling the full recreation of financial systems on the internet. Circle's business is divided into three main parts.
The first is USDC, the digital dollar or sometimes called Stablecoin. We have created an open network where users can create digital wallets, trade, and connect payment platforms, enabling people to send and receive digital dollars worldwide nearly instantly at very low costs.
The second part involves building underlying infrastructure to allow financial and economic activities to operate on the internet, including Arc blockchain, a new infrastructure we developed, which we view as an operating system for the economy.
The third part is developing a payment network that enables financial institutions worldwide to transfer money across countries and currencies within minutes, reducing costs and delays associated with international money movement.
Jeremy revealed that the reason for participating in the IMF-World Bank Group Annual Meetings is that Circle currently works with these organizations and many member countries, particularly focusing on emerging market movements to adopt this technology to increase financial service access and improve financial system efficiency. Has Stablecoin entered the mainstream yet?
"We also see businesses and households in many markets holding more digital dollars as an alternative to their domestic banking systems. Additionally, major payment companies, capital market firms, global banks, tech companies, and e-commerce businesses are integrating USDC into their products."
Last week, the company announced a partnership with a project related to SAP, integrating USDC payments into enterprise resource planning systems, enabling large companies' treasury departments to automate global payment transactions via USDC.
Another critical turning point is the new US regulatory framework for Stablecoins, effective January 2027, marking an important industry development and reflecting the US government's emphasis on preserving the US dollar's role and competitiveness in the global financial system.
"We are seeing Stablecoins permeate nearly every economic sector, and this transformation is accelerating,"
Jeremy said.Traditional financial institutions are alert and opening paths for more Stablecoin adoption.
Jeremy
said that currently, CBDCs have limited real-world usage, and most tokenized deposits remain in pilot phases. Conversely, Stablecoins are already in significant use, with transaction volumes in the trillions of dollars. "I view this through the same principle as the internet's functioning. People want communication tools that are interconnected and information accessible via the internet. The same principle applies to money."
Jeremy
expressed his belief in market competition, technological innovation, free and competitive markets, and sound regulation, which allow broader participation in the industry. Traditionally, financial institutions created closed payment systems usable only among certain institutions, limiting system benefits. In contrast, Stablecoin networks like USDC offer open, public services accessible worldwide by anyone. There are also increasing signs of large financial institutions responding to customer demand. Jeremy
cited examples such as major banks like Citibank, The Bank of New York Mellon Corporation (BNY), and Standard Chartered, which currently provide services enabling institutional clients to access or use USDC. Asia is Circle's largest market. Jeremy
Asia plays a critical role in global trade, both within the region and with other continents. Many businesses need to issue invoices and receive payments in US dollars, making Stablecoins an efficient method for these transactions. "We also observe increasing Stablecoin roles in trading, investment, and savings. Digital financial platforms are popular across Asia, especially among younger generations, who view these platforms as financial hubs on their mobile phones. They can hold digital dollars, invest, earn returns, and make cross-border payments. I believe we are witnessing the emergence of a global financial Super App, with Asia as a key market for this transformation,"
Jeremy said.
What about Thailand? Where are the opportunities, and what should Thailand do correctly to seize them?Jeremy outlined three main areas where Thailand can benefit. First isCross-Border Payment.Thai households and businesses dealing with foreign individuals or companies need secure, efficient, and cost-effective transaction methods. Stablecoins can reduce steps and costs, speeding up money transfers.

Jeremy
said this presents opportunities for Thai fintech firms, digital asset trading platforms, brokerage companies, and banks to integrate Stablecoins into their international transaction products and services. Next is Global Investment.
Digital financial platforms can help people in various countries access global markets for saving and investing more efficiently. Thailand should consider how to enable its citizens to access these markets. Finally, there is
Domestic Scalability, or upgrading the baht to a blockchain-based digital currency, also known as On-chain Currency. Jeremy believes that all global currencies can benefit from becoming On-chain currencies running on blockchain networks. Such money can be programmed to operate under defined conditions—Programmable Money—and support new uses that traditional money, confined to bank accounts or government accounts, cannot handle conveniently. Especially as the economy becomes more digital and AI plays a greater role, we will need money that software and AI agents can use efficiently. For Thailand, this may require a digital baht in On-chain form, and a baht-pegged Stablecoin will be vital for both domestic use and global market connectivity.
From cross-border payments to baht-pegged Stablecoins. However, an important question is whether developing a Thai Stablecoin would affect baht stability or the Bank of Thailand's ability to manage the financial system.
Jeremy
"The key is appropriate regulation aligned with the central bank's objectives. Stablecoin issuers should be regulated, and the reserves backing Stablecoins must be managed securely and transparently."
Issuers can create what we call a Narrow Bank structure, focusing on holding and managing reserves separately from other company assets. Circle operates through a National Trust Bank structure under US regulation. Thailand can consider regulatory frameworks placing Stablecoin issuers under relevant authorities and establishing protections for reserves backing baht-pegged Stablecoins, possibly involving central bank reserve management.This approach would allow the private sector to innovate in digital money usage while maintaining regulation and reserve protections. Jeremy affirmed that well-designed regulation will not conflict with policy goals but will support the central bank's objectives.
Jeremy
revealed that Circle has previously engaged with the Bank of Thailand, which has conducted Sandbox trials where USDC was used in some projects, including participation by commercial banks and fintech companies contributing innovations to these trials.
Regarding regulatory progress in the region, Hong Kong, Japan, Singapore, and South Korea are advancing Stablecoin regulatory frameworks in different forms, and
Jeremy said Thailand will follow soon. Regarding business cooperation, Circle sees significant opportunities in Thailand. Some regulated crypto platforms in Thailand already support USDC, while payment companies, investment firms, and banks are evaluating how to leverage this technology.
Both USDC, Arc, and our payment network development projects offer opportunities for collaboration with traditional financial institutions in various forms. We are doing this in many countries and believe there will be good cooperation opportunities with leading Thai companies. In the next 10 years, Stablecoins will become part of our daily lives. Looking ahead 10 years,
Jeremy
believes Stablecoins may no longer be a term people mention because digital money will become an integral part of daily life, much like the internet is used today without much thought about the underlying technology.
Jeremy said, "People will recognize its benefits because Stablecoins enable things previously impossible. They will have easier, safer, and lower-cost access to financial systems and new opportunities to participate in the global digital economy."
For Thailand, the question is how long it will take to reach that point and how to establish rules that allow this technology to grow effectively, benefiting businesses, investors, and the Thai economy. Read stock and investment news with Thairath Money to help you "Better Finance, Better Life" at https://www.thairath.co.th/money/investment
Follow the Facebook page: Thairath Money at this linkhttps://www.facebook.com/ThairathMoney
