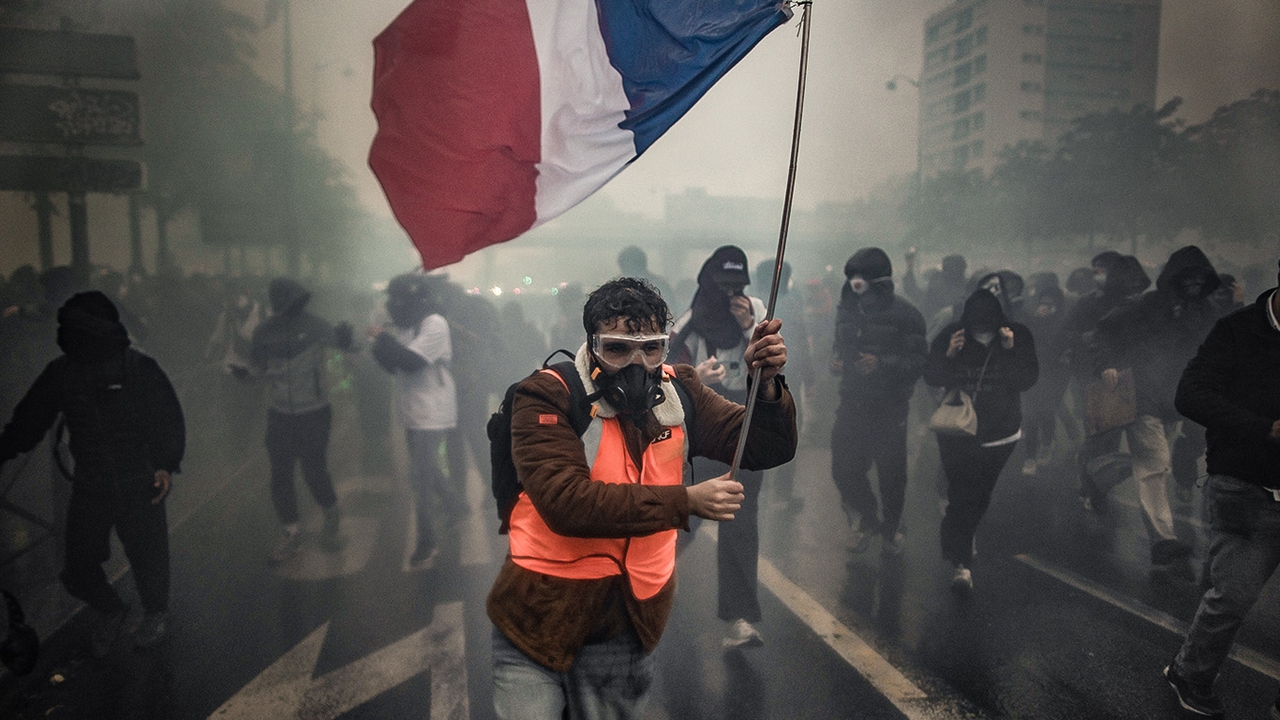
The unrest in France continues, drawing global attention to the fiscal pressures the country faces as the largest welfare state in Europe. What began as protests over school issues has expanded into nationwide demonstrations demanding relief from high living costs and inadequate public services.
The situation escalated last week with damage to landmarks, arson, store invasions, thefts, clashes causing injuries, and arrests. Although tensions have eased somewhat, economic concerns persist.
These protests reveal deeper economic problems beyond public dissatisfaction: France struggles to balance its large welfare system and government spending with chronic budget deficits, rising debt servicing costs, and sluggish economic growth.
Investors have grown increasingly worried after French government borrowing costs hit their highest since 2002 last week. Analysts warn prolonged unrest could harm economic growth, undermine investor confidence, and complicate government austerity plans.
The impact extends beyond France. Rising borrowing costs, uncertainty over the new budget, and the upcoming 2027 presidential election raise concerns about France’s fiscal credibility and risks potentially affecting the broader Eurozone economy.
France’s economic problems have deep roots, dating back to the COVID-19 pandemic, energy crises from the Russia-Ukraine war, and recent geopolitical turmoil—all increasing government expenditure burdens.
However, the core problem remains that France’s government spending significantly exceeds its revenue.
France’s welfare system covers pensions, healthcare, education, and other public services, mainly funded by tax revenues and social security contributions.
This system provides broad economic and social security for households, protecting against daily life risks, but also results in the government bearing massive and ongoing expenditure obligations.
When spending exceeds revenue, the government must borrow to cover deficits. Repeated deficits increase public debt, along with future principal and interest payments the government must service.
Although France reduced its budget deficit from 5.8% of GDP in 2024 to 5.1% in 2025, public debt continued rising. According to France’s National Institute of Statistics and Economic Studies (Insee), by end-2025, public debt reached 3.46 trillion euros, or 115.6% of GDP, expected to rise to 118.1% in 2026.
At the same time, economic growth forecasts for 2026 were lowered to just 0.5%, while the budget deficit is expected to increase to 5.4% of GDP.
The Organisation for Economic Co-operation and Development (OECD) reported that since 2023, France’s economy has grown on average only about 1.4%. This low growth limits tax revenue expansion, making deficit reduction difficult without tax hikes or spending cuts.
Currently, the French government is attempting to restore fiscal discipline, cautiously balancing measures so as not to worsen consumption, investment, or public confidence. However, this is increasingly difficult as borrowing costs rise and political resistance to spending controls intensifies.
Starting with the pension system, one of France’s most politically sensitive issues, as it directly affects the country’s fiscal status, demographics, and public expectations of welfare.
France is becoming an aging society with longer life expectancy, meaning the government and pension system must pay retirees for longer periods. Meanwhile, the working-age population paying taxes and social contributions may not grow at the same pace as retirees.
From a fiscal perspective, growing reliance on public budgets for pensions reduces funds available for education, healthcare, infrastructure, or national defense—all competing for limited budget allocations, while the government must also reserve money to service existing debt.
Next is the education system, which sparked youth protests over overcrowded classrooms, teacher shortages, and school buildings needing repair or lacking adequate infrastructure to handle rising temperatures.
With public service quality declining despite consistently high household taxes, protests have expanded beyond education to include issues of living costs and dissatisfaction with government management.
France already has high tax rates, limiting the government’s ability to raise additional revenue. Key tax rates include:
Additionally, France faces global geopolitical uncertainties. Middle East conflicts increase energy price risks; the Russia-Ukraine war and broader security concerns are prompting European governments to reassess defense budgets.
Rising energy costs affect the economy in many ways: for households, higher prices reduce purchasing power; for businesses, production and transport costs rise, potentially pushing inflation higher.
If the government subsidizes energy prices or increases financial aid, public spending rises; if subsidies end or taxes increase, household disposable income declines.
Another key issue is deep political division. The right and left sharply disagree on tax policies, immigration, pensions, public investment, and social welfare, making budget deficit reduction agreements difficult.
Cutting spending risks greater public opposition; raising taxes may hurt household purchasing power and private investment. Uncertainty about passing credible budgets politically worries investors.
France’s challenges offer a vital lesson: when public debt, borrowing costs, and political resistance to reforms rise simultaneously, governments have fewer options to resolve problems, even as citizens most need support.
France’s situation highlights the importance of assessing long-term impacts of repeated budget deficits and policies that create permanent government spending commitments.
Fiscal discipline doesn’t necessarily mean cutting welfare or social aid but ensuring welfare policies, investments, and obligations have reliable funding sources and can be sustained.
As Thailand faces pressures from an aging society, rising healthcare costs, and growing development investment needs, preserving fiscal space to maintain budget capacity for future crises becomes increasingly critical.
Sources: CNBC [1][2],Firstpost,Yahoo! Finance,Financial Times
For economic and government policy news, visit Thairath Money for your "Better Finance, Better Life" athttps://www.thairath.co.th/money/economics
Follow the Facebook page: Thairath Money at the link belowhttps://www.facebook.com/ThairathMoney