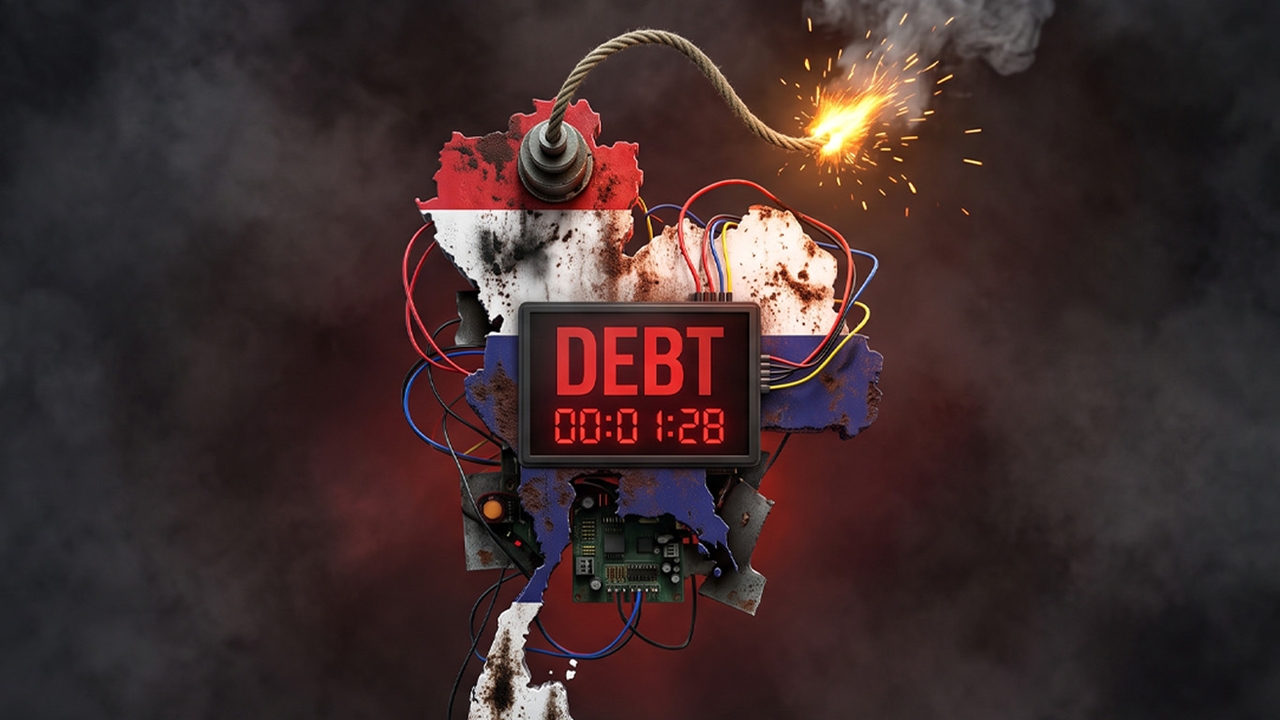
Thailand's economy in 2026 faces uncertainty but holds both hope and fragility, especially regarding debt issues, with household debt remaining high and public debt nearing its ceiling.
These two issues limit consumer spending and government policy measures. However, Thailand's major challenge is to move forward and grow the economy. How will these challenges be managed?
As 2026 nears its end, the National Economic and Social Development Council (NESDC) projects Thailand's economy to grow between 2.0 and 2.5%. The International Monetary Fund (IMF) has also raised its forecast for Thailand's 2026 GDP to 2.1%, up from a previous estimate of around 1.9%, partly due to gains from technology and AI-related industries.
Despite this positive news, looking ahead to 2027, Thailand's GDP growth may slow. Many believe the benefits from government economic stimulus measures are short-lived. Structural challenges remain, including an aging society reducing the workforce and the dual debt problems.
The first dimension is the "household debt" problem. The latest data from the Bank of Thailand (BoT) shows that household debt outstanding in Q2 2026 reached 16.4 trillion baht, reflecting many Thais facing tight cash flow.
Household debt to GDP stood at 85.2% in Q2 2026, a high level that may impact spending and consumption. Kasikorn Research Center notes that although this ratio slightly declined from 86.0% the previous quarter, debt relative to household income remains high—about 1.5 times income on average since 2023—indicating debt burden pressure persists.
The second dimension is the "public debt" issue. Latest data from the Public Debt Management Office (PDMO) reports that as of 31 August 2026, public debt to GDP was 67.94%, close to the 70% debt ceiling. There has been discussion about raising this ceiling to provide the government with more fiscal space to handle unforeseen circumstances.
On the other hand, KKP Research analyzes that Thailand's public debt ratio nearing the legal 70% limit restricts fiscal policy space. Rising energy prices due to the Middle East conflict affect citizens, and if the economy slows, public debt may increase further. Monitoring how the government addresses these issues is crucial.
Regarding whether Thailand's debt issues will improve this year, Kasikorn Research Center expects household debt to GDP may decrease to 84.0% by end-2026 (down from 86.8% at end-2025) as debt growth slows relative to nominal GDP. However, households face tight income and liquidity, limits on new borrowing, and existing debt continues to constrain purchasing power, weighing on economic recovery.
The Bank of Thailand continues addressing household debt with measures targeting various problems, such as encouraging debt restructuring before default, debt clinic programs to assist distressed debtors, debt consolidation to lower interest burdens, and easier debt management. These programs' long-term outcomes are still being monitored, and BoT is expected to expand measures to help new target groups.
Regarding public debt, Dr. Arkhom Termpittayapaisith, Deputy Prime Minister and Minister of Finance, has stated that Thailand's current situation differs greatly from the 1997 financial crisis. Lessons have been learned, and fiscal stability has been strengthened. Thailand's foreign reserves are nearly three times its short-term debt, providing strong protection against risks.
Finally, KKP Research views that the key to resolving public debt issues is improving fiscal spending efficiency and value, starting with tax revenue reform and structural adjustments. The government should also implement targeted measures focused on those truly in need.
Sources: Kasikorn Research Center, Bank of Thailand, NESDC, PDMO.
Follow economic and government policy news with ThairathMoney athttps://www.thairath.co.th/money/economics/thai_economics
Follow the Facebook page: Thairath Money at this link https://www.facebook.com/ThairathMoney