Land priced at 3.9 million baht per square wah may seem far removed from most people's reality. However, as such historic land parcels gradually transition from undeveloped assets into ultra-luxury condominiums, a more intriguing question arises beyond the purchase price.
That question is: who will pay for these assets, and how will real estate developers generate value to recoup their enormous costs?
Data from Savills (Thailand), a real estate consultancy, summarizes the top five highest-priced land transactions in Thailand. This data illustrates that competition to own land in central Bangkok is not new but has been ongoing for many years in the country's prime locations.
One of the most striking aspects of the high-end real estate market is the disparity between land price units and residential sale prices.
For example, Sarasin land sold for approximately 3.9 million baht per square wah, while prices for Ultimate Class condominiums in prime locations approach one million baht per square meter. Considering construction costs, common area expenses, design fees, financing, and development costs, it is clear that developers face challenges beyond acquiring prime land.
The higher the land cost, the more a project must generate revenue per area through sale price, appropriate unit count, space design, and product positioning that differentiates it from typical condominiums.

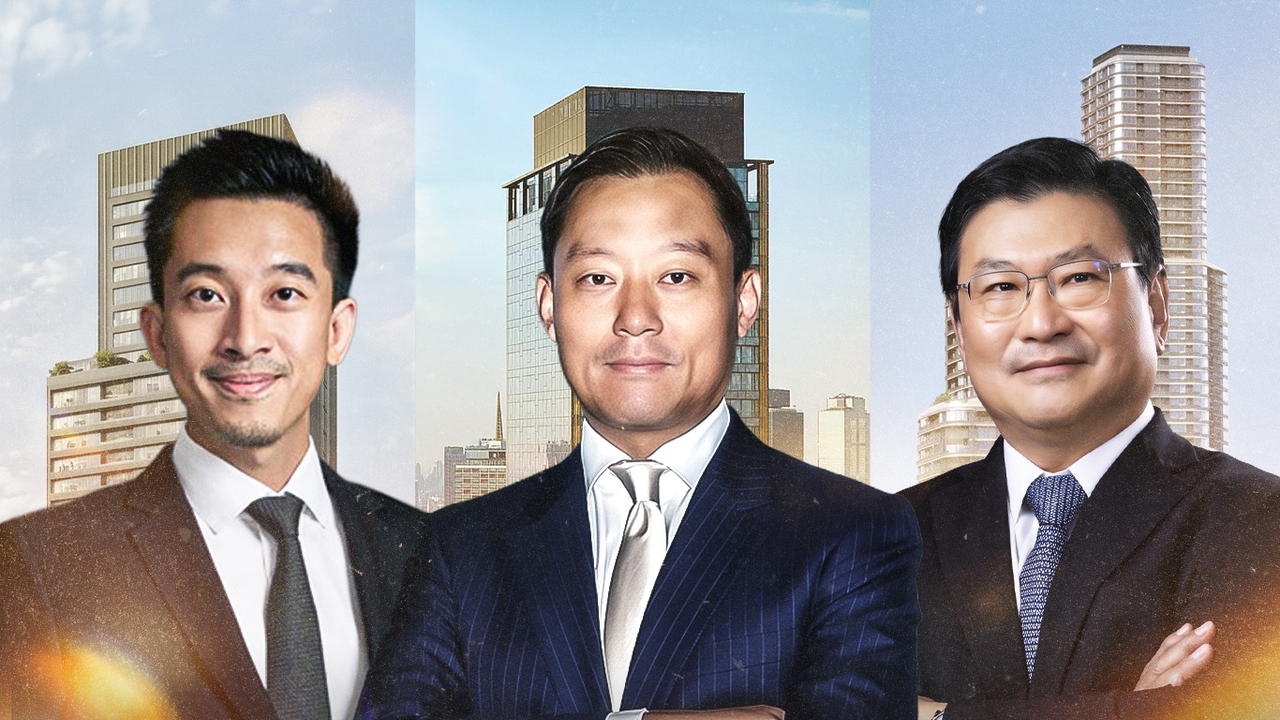
The latest major news is a clear example: Rosewood Residences Bangkok, developed by SC Asset (managed by Natthapong Kunakornwong) in partnership with Tokyo Tatemono Group, on the former Sri Fuang Foon building site in Sarasin area.
The project consists of only 85 units in a 37-story building on 2 rai 1 ngan 87 square wah of land, with estimated selling prices exceeding 550,000 baht per square meter.
A simple calculation dividing the 3.5 billion baht land value by 85 units yields an average land cost exceeding 41 million baht per unit.
However, this does not mean each unit has the same land cost or must sell for 41 million baht to break even, as common areas, unit size differences, and other cost factors play roles. Still, it clarifies the scale of the business challenge.
Furthermore, Pattrachai Taweewong, Senior Director of Market Research and Communications at Savills (Thailand), analyzed that the project reflects premium land values and increasing competition in the upper market segment, particularly branded residences, which have elevated Thailand to a leading position in the Asia-Pacific region by completed projects and among the top 10 globally.
This trend stems from rising demand for Ultimate Class residences, significant growth in high-net-worth individuals (HNWIs) and ultra-high-net-worth individuals (UHNWIs) in the region.
The entry of global brands raises value, differentiation, and project identity. Thailand currently has about 18,801 branded residence units, worth approximately 220 billion baht.
By 2026, Savills forecasts around 650 new branded residence units will launch, a 32% increase from the previous year, with Bangkok and Phuket remaining the primary markets driving domestic growth.
Savills' report on Branded Residences also highlights that branded properties can command a premium over non-branded counterparts. A recent global study found an average price premium of about 31% compared to comparable non-branded properties.
Importantly, this 31% figure is a global average across many markets and does not guarantee that every branded condominium in Thailand will automatically sell for 31% more.
From buyers’ perspective, this premium may reflect brand reputation, design standards, services, privacy, and confidence in the living experience.
From developers’ viewpoint, it is a strategic question: partnering with global brands entails costs and business conditions, and whether the premium can be realized depends on location, project quality, and market demand.

The new price ceiling test becomes clearer through flagship project activity in 2026, especially in coveted locations as follows.
Savills (Thailand) assesses that the simultaneous launch of these magnet projects in freehold central city locations will significantly propel Thailand’s Ultimate Class condominium market beyond the "one million baht per square meter" threshold soon, especially in Lumphini, Rama 4, and inner-city areas featuring prime location, design, architecture, and global brand collaborations.

As historic land parcels enter development, the market faces another question: its capacity to absorb high-end supply.
Savills estimates that Ultimate Class condominium prices in prime Bangkok locations may continue rising soon, supported by high land costs, unique projects, and demand from affluent buyers.
However, price forecasts do not guarantee full market acceptance. Key factors to watch include the pace of new project launches, sales velocity, actual closing prices, proportions of buyers purchasing for residence versus investment, and competition among nearby projects.
If multiple developers adopt similar strategies—selecting central city locations, partnering with global brands, and targeting the same market segment—the differentiators may become the new standard, while higher prices face real purchasing power limits.
Conversely, scarce central city land offers locational advantages and supply constraints, which could help some projects maintain differentiation long-term. Whether this advantage translates into good returns depends on total costs and actual sales results.
Ultimately, expensive land does not guarantee project success, nor does a famous brand ensure target prices are achieved. The true challenge in the high-end property sector lies in converting scarce locations into products with rational, distinct value and finding customers willing to pay for that value.
Read economic news and government policy with ThairathMoney for "Better Finance, Better Life" at
Follow the Facebook page: Thairath Money at this linkhttps://www.facebook.com/ThairathMoney