

Small and medium-sized enterprises (SMEs) are a crucial part of Thailand's economy, accounting for over 50% of employment nationwide. However, with the recent economic slowdown, some SMEs have seen sales decline, and those with limited cash flow may face closure. To survive, they need to invest to compete with larger firms. Yet, bank lending to SMEs has been declining for over 17 consecutive quarters.
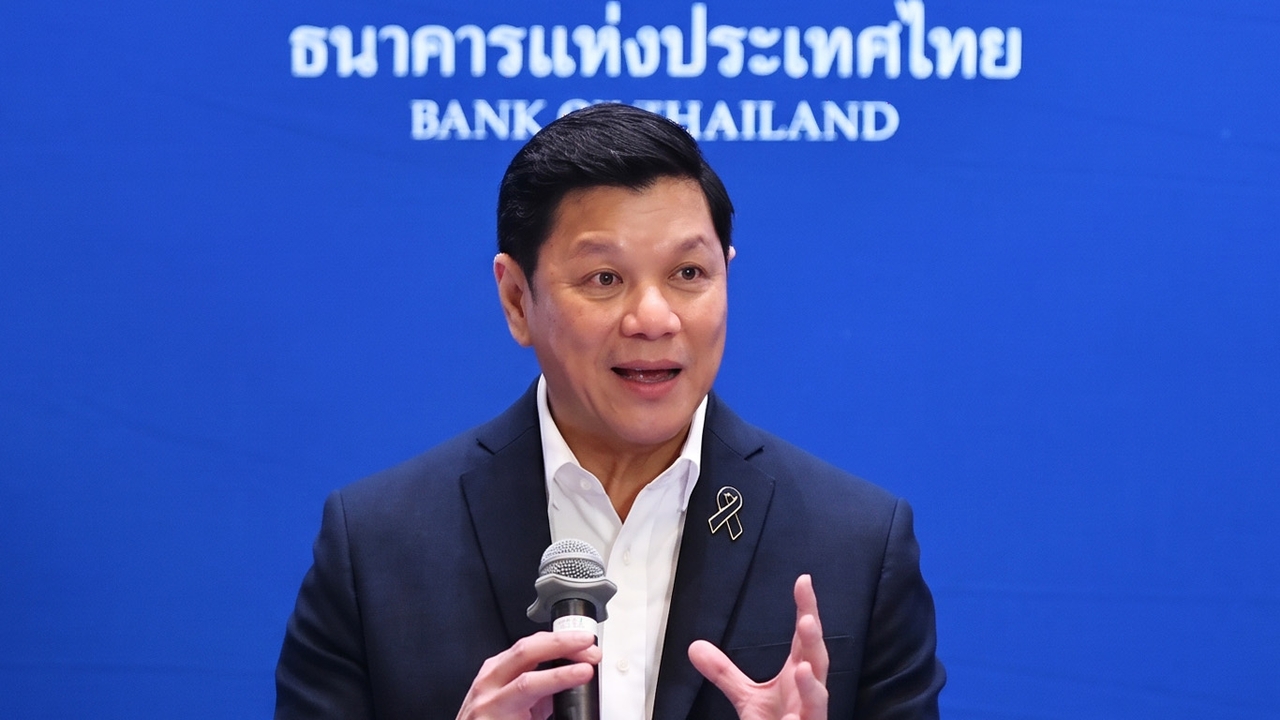
Recently, the issue of SME access to credit was raised by Dr. Somchai Sajjapongse, Governor of the Bank of Thailand, in an open letter to the media. The Bank of Thailand then held an urgent press briefing on 16 Nov 2026.
What are the key points and perspectives the public needs to know? Thairath Money has summarized them in this article.
Let's begin with information from the Puey Ungphakorn Institute for Economic Research (PIER). PIER explains that being an SME is challenging due to ongoing business obstacles. Data shows about 30% of SMEs cease operations within five years. Firms started after 2013 experience revenue stagnation around the five-year mark, and the number of businesses with chronic non-performing loans has been steadily rising.
On the other hand, there are SMEs with strong potential that often face difficulty obtaining loans during their startup phase. A study titled “Misallocation: The Major Challenge for Thailand’s Financial Sector to Enhance Economic Potential” found that the top 30% most efficient SMEs receive about 20% of loans compared to 60% for large businesses. Among these, businesses younger than five years obtain only 12% of bank loans, compared to over 40% for those older than 25 years. This data suggests lenders may not fully recognize the potential of new or SME businesses.
Looking at the bigger picture, recent data from a press conference summarizes commercial bank lending in Q3 2026 (16 Nov 2026). Overall, commercial bank loans increased by 4.0% year-on-year, driven by a 10.4% growth in loans to large businesses. Consumer loans dropped slightly by 0.5% but showed improvement in various categories such as housing loans, credit cards, and personal loans, except hire-purchase loans which remain negative.
Meanwhile, SME loans declined by 4.2%, marking 17 consecutive quarters of decline since Q3 2022. This is partly due to contraction in small SMEs in trade and tourism, while sectors related to AI and construction continue to grow well.
Additionally, the non-performing loan (NPL) ratio for SMEs is highest at 9.1%, followed by consumer loans at 3.3%, and lowest in large businesses at 1.3%. With high household debt and rising living costs, lenders tend to prioritize lower-risk loans to maintain profits. How does the Bank of Thailand view this issue?
At the press briefing, Vittaya Ratanakorn, Governor of the Bank of Thailand, said that recently, the Bank of Thailand has expanded its role from overseeing three stability pillars to also supporting the economy by addressing structural problems.
“GDP growth is too low, not 5% like before. The low growth causes people to lack money, leading them to borrow, increasing NPLs and household debt. SMEs face problems, becoming structural issues that drag GDP down and ultimately affect stability,” Vittaya explained.
Therefore, the Bank of Thailand’s mission to help resolve structural problems focuses on four main areas: 1) household debt, 2) SME credit access, 3) fair financial service fees, and 4) management of shadow money and corruption flowing through financial institutions.
Regarding SMEs, Vittaya added, “Supporting SMEs is not a direct responsibility of the Bank of Thailand; it is a role we have expanded into to assist. It requires collaboration across all agencies.”
The Bank of Thailand has continuously addressed SME credit access through at least two projects:
Finally, Governor Vittaya clarified that amendments to the Bank of Thailand Act have no relation to the negative trend in SME loans. The Act’s revision was acknowledged in meetings without approval to amend, with prior studies confirming the current law’s effectiveness and relevance.
For more information on economic data and government policies, follow ThairathMoney athttps://www.thairath.co.th/money/economics/thai_economics
Follow the Thairath Money Facebook page at this link: https://www.facebook.com/ThairathMoney