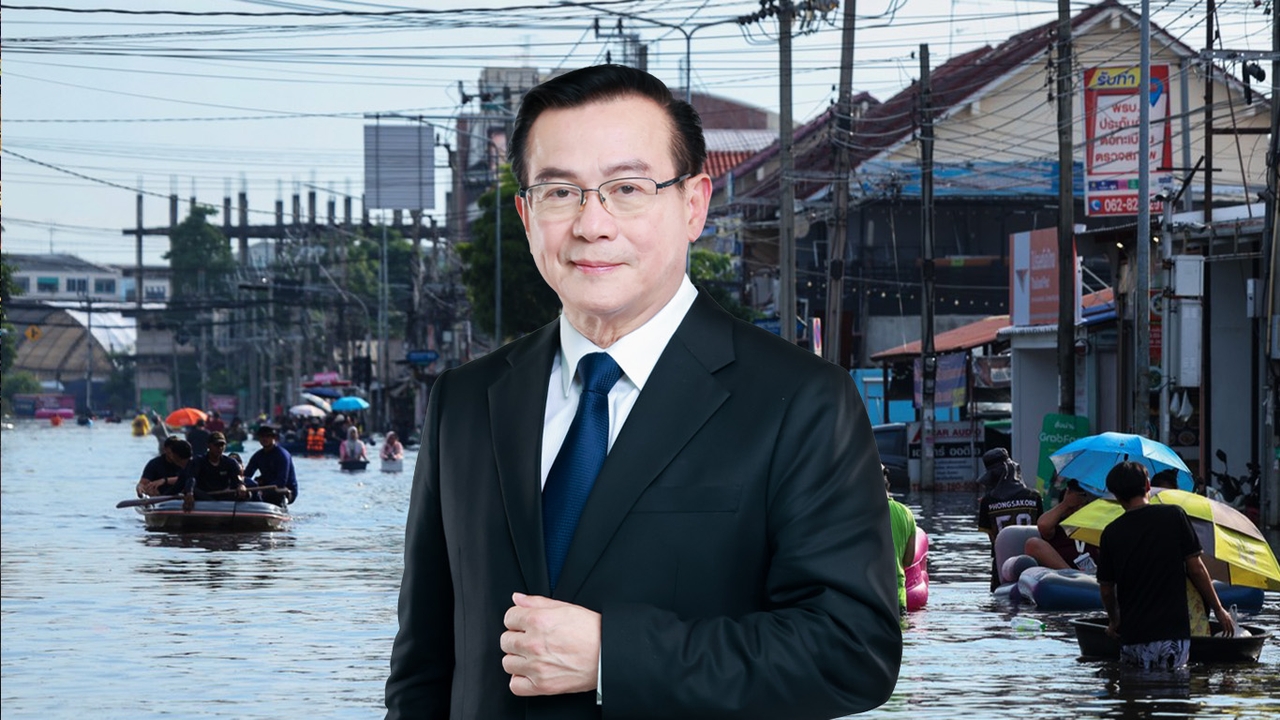
"Anything can happen." This phrase likely comes to mind after Thailand experienced a major earthquake early last year, floods in Hat Yai and the northern region later that year, and recently, heavy rainstorms in Bangkok and 27 other provinces causing flooding up to neck level. Many expect disasters may occur more frequently due to climate change.
Recently, the government sought ways to respond, resulting in the establishment of the “National Disaster Insurance System,” purchasing insurance coverage worth 15.5 billion baht, which begins today (1 Oct 2026).
Dr. Somporn Suebtawilkul, CEO of Dhipaya Group Holdings Public Company Limited and President of the Thai General Insurance Association, held a press conference this afternoon outlining key information the public should know. 1. What is the National Disaster Insurance System?
The government allocated a budget of 15.5 billion baht to purchase insurance for Thai citizens focusing on three main disaster coverages: windstorm (including storms and lightning), flooding, and earthquakes. Coverage runs from 1 Oct 2026 to 1 Oct 2027.
Initially, it will cover about 29.8 million Thai households, focusing on residential homes and accident insurance for those affected by disasters.
2. Can claims be made for disasters before 1 Oct?
The answer is no. Damage caused by existing floodwaters before coverage starts is not covered (coverage begins for one year starting 1 Oct 2026). However, citizens can report damages and receive government relief as usual (e.g., initial assistance of 9,000 baht per household).
3. How much coverage for homes affected by flooding?
The government purchased a "Group Home Insurance Policy to Assist Disaster Victims" with primary conditions covering residential homes up to 100,000 baht per household, divided as follows:
Flooding: Initial payment of 10,000 baht without waiting for assessment, with additional payments up to 90,000 baht based on actual damage, totaling a maximum of 100,000 baht per incident per household.
- Windstorm/lightning and earthquake/tsunami: Initial payment of 5,000 baht, plus additional payments up to 95,000 baht based on actual damage, totaling up to 100,000 baht per incident per household.
- 4. Death or permanent disability due to disaster
The government purchased a "Group Accident Insurance Policy to Assist Disaster Victims" with a premium budget of 500 million baht. It covers death or total permanent disability caused by accidents related to disasters, as follows:
In case of death from a disaster, coverage is 2,000,000 baht per person according to policy terms, paid to legal heirs.
- In case of total permanent disability (unable to work), payment is 200,000 baht per person.
- 5. Important conditions to know before claiming!
Must be Thai nationals with Thai citizenship and a national ID card, along with proof confirming Thai nationality.
- The home must be a regular residence, have a house number, or if no house number, be habitable and listed under the Department of Provincial Administration as of 15 Sep 2026.
- Covered assets include the house structure and built-in furniture, excluding movable furniture and electrical appliances.
- The area must be declared a disaster zone; if flooding occurs temporarily without declaration, it is not covered under disaster insurance terms.
- 6. If one person owns multiple houses, can they claim?
Regardless of the number of houses (including rented ones), if affected by flood and regularly occupied, meeting the above conditions, coverage applies per household. Separate claims can be made based on actual damage, up to 100,000 baht per house.
However, abandoned houses (uninhabitable) or non-primary residences may not be eligible, depending on policy terms.
7. Can flooded condominiums claim?
For condominiums with registered separate house numbers per unit, each unit is distinct. Damaged units can claim coverage up to their individual insured amounts.
8. What if water surrounds the house? Is it claimable?
Claims are allowed. Even if the house structure is undamaged, if floodwaters surround the building—such as water encircling the house but not the entire village or outer roads—persistently affecting regularly occupied homes and making normal living impossible for over 7 consecutive days, an initial compensation of 10,000 baht per household will be paid.
9. How to claim for repeated flooding?
If a flood was previously claimed or a new flood wave occurs during the policy period, claims are allowed up to a maximum of 100,000 baht “per event per household.”
For example, if a house was flooded during the first rain wave and claimed, but floods again, a new claim can be made. The insurer will pay an initial 10,000 baht and assess further damage to cover repairs restoring the home to its pre-flood condition.
10. How prepared are insurers to handle claims?
The two group policies’ total premium is 15.5 billion baht but provide coverage up to five times that amount, or 75 billion baht. Due to the high coverage, participating insurers have managed risk through reinsurance. The Thai General Insurance Association has negotiated full 100% reinsurance coverage with international reinsurers.
Therefore, the Thai insurance industry is ready to provide coverage according to the government-purchased group policies. The coverage aligns with the government’s budget and is based on thorough analysis, statistics, and risk calculations from historical data.
11. List of insurance companies participating in the project
Eleven leading general insurance companies are involved, including:
Bangkok Insurance Public Company Limited
- Krungthai Panich Insurance Public Company Limited
- Tokio Marine Insurance (Thailand) Public Company Limited
- Dhipaya Insurance Public Company Limited
- Thai Paiboon Insurance Public Company Limited
- Thai Vivat Insurance Public Company Limited
- Falcon Insurance Public Company Limited
- Muang Thai Insurance Public Company Limited
- Viriyah Insurance Public Company Limited
- MSIG Insurance (Thailand) Public Company Limited
- iCare Insurance Public Company Limited
- 12. Measures against fraudsters who may exploit the system
The government and the association have established tight security systems to prevent fraud, including:
SMS from the program will be used only to provide official information or links to official channels.
- No requests for OTP codes will be made.
- No requests for money transfers to receive compensation will be made.
- To combat insurance fraud, since insured persons will submit evidence such as photos of damage, the association will apply AI technology to distinguish genuine images from edited ones and thoroughly verify facts.
13. How to contact for claims
Claims can be made through four main channels: the website (https://www.ThaiNatCat.org), LINE Official Account (@Thainatcat), call center at 0 2012 5555, and local claim reporting points.
Regarding claim timelines:
Home damage claims are divided into two parts:
- - Initial compensation of 10,000 baht will be paid within 15 days from receipt of complete documents and information by the insurer, not from the claim notification date.
- For additional compensation after damage assessment and agreement with the insured, payment will be made within 15 days from receipt of complete information and documents.
Life damage claims will also be processed within 15 days upon receipt of complete information and documents. - 14. How to prepare documents for claims
Recommended documents and evidence for initial damage claims include:
1. National ID card of the claimant
2. Proof of ownership of the residence
3. House registration of the damaged residence (if available)
4. Photographs showing the damage to the residence
5. Bank account information or passbook, in case payment cannot be made via PromptPay linked to the national ID
For those seeking additional claims for greater damage, prepare supporting evidence such as:
1. Additional photos showing detailed damages
2. List of damaged property or parts of the residence
3. Repair estimates, receipts, or proof of repair expenses (if any)
4. Other documents or evidence requested by the insurer or program
Compensation will be based on actual damage value within the policy limits and conditions.
15. If a home already has insurance, can it claim under this program?
Yes, claims can be made if the insured meets the qualifications and damage complies with the terms and conditions of the specified insurance policy.
Read personal finance and financial planning news with Thairath Money to help you "Better Finance, Better Life"
https://www.thairath.co.th/money/personal_finance