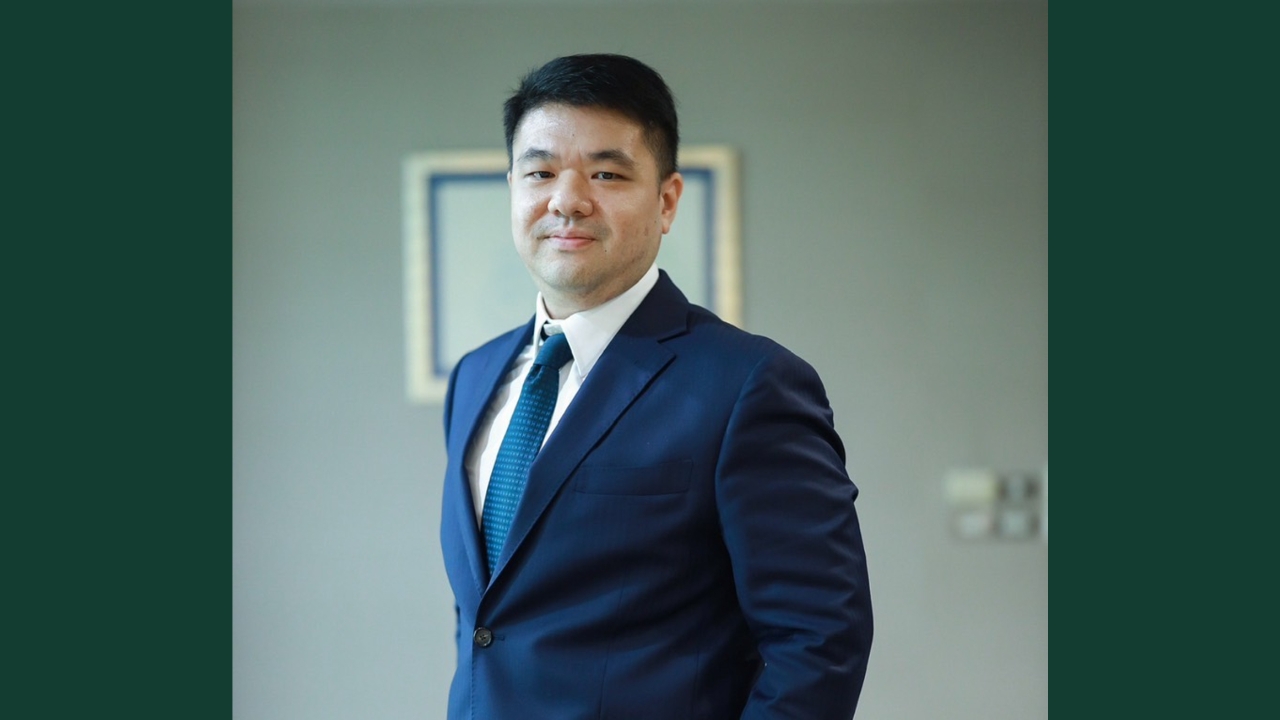
Pachara, a Securities and Exchange Commission board member, points out that based on the Bangkok Blueprint cooperation framework addressing crypto issues, Thailand must urgently close legal loopholes and proposes four measures to curb cyber financial crimes related to cryptocurrencies.
Mr. Pachara Naripthaphan, a board member of the Securities and Exchange Commission (SEC), spoke about the Bangkok Blueprint cooperation framework, an outcome from the IMF-World Bank 2026 forum held in Bangkok this year. He said this cooperation was established specifically to tackle financial crime, which has expanded recently due to AI. It marks a positive step for Thailand aligning with the signing of the United Nations Convention against Cybercrime in Hanoi last year.
Although Thailand has yet to ratify the convention, which requires 40 countries to ratify before it becomes binding—with only Qatar, Azerbaijan, and Vietnam having done so—this does not mean Thailand is exempt from adhering to the treaty. According to Article 18 of the Vienna Convention on the Law of Treaties, a state that has signed but not ratified must not act in a way that defeats the treaty's object and purpose before it enters into force. This means Thailand must promote and enhance effective cybercrime prevention and suppression measures, facilitate and strengthen international cooperation against cybercrime, and support related technical assistance.
The Bangkok Blueprint thus represents a good intention that builds a certain level of confidence. However, discussions at the forum highlighted AI’s growing role in the increasingly complex financial business world, particularly regarding the use of digital assets to move funds. This presents a challenge that must be addressed alongside strengthening measures to prevent cyber financial crimes that exploit technology to evade legal penalties.
Currently, fundraising through digital security tokens, or Security Token Offering (STO), awaits amendments to the Securities and Exchange Act B.E. 2535 (1992) to support technology-based fundraising, which would reduce costs and improve accessibility. Properly designed regulations could benefit SMEs and retail investors by making capital markets more accessible.
Lastly, there is a need to change perspectives on law enforcement efficiency, investigation processes, overlapping agencies, and penalties. Mr. Pachara sees these as major challenges given the complexity of current transactions migrating into the digital asset world, where cross-border trades occur instantly. This dual-edged sword faces a bureaucracy focused more on process than regulatory capability. Regulatory bodies and other state agencies outside the bureaucracy must be improved to fulfill their original purposes, ensuring standards and agility, especially by eliminating overlaps in the justice system. For example, the Administrative Court Act, designed to oversee bureaucracy, should not regulate agile agencies but rather those should be under the regular courts to maintain uniform standards with the business sector, similar to OECD countries. The four approaches to detect, monitor, and prevent cyber financial crime that he sees as initially feasible to address current loopholes are:
1) Clearly define regulatory agencies’ responsibilities, focusing on consumer protection.
2) Educate society about the roles of these agencies to prevent misconceptions or inflated expectations.
3) Use existing regulations effectively by eliminating useless or unused rules to reduce regulatory loopholes.
4) Develop understanding of the international context to frame necessary and beneficial data exchanges supporting Thailand’s economy.
“From the Bangkok Blueprint to the challenge of using digital assets linked to international financial crime, this is a new problem built on old issues. It requires technological understanding to avoid reactive fixes after problems arise. Thailand should build an architecture alongside positioning itself as a trustworthy regional financial hub. It must avoid crossing lines that harm economic confidence or doing too little that undermines economic trust. Regulatory design must be balanced and effective rather than overly restrictive or alarmist, which would damage investment credibility,” Mr. Pachara concluded.