The government is preparing a new tax credit system to attract investment, allowing credits to be used for tax payments and the remaining balance refunded in cash under specified conditions. The business sector is invited to provide feedback by 5 November.
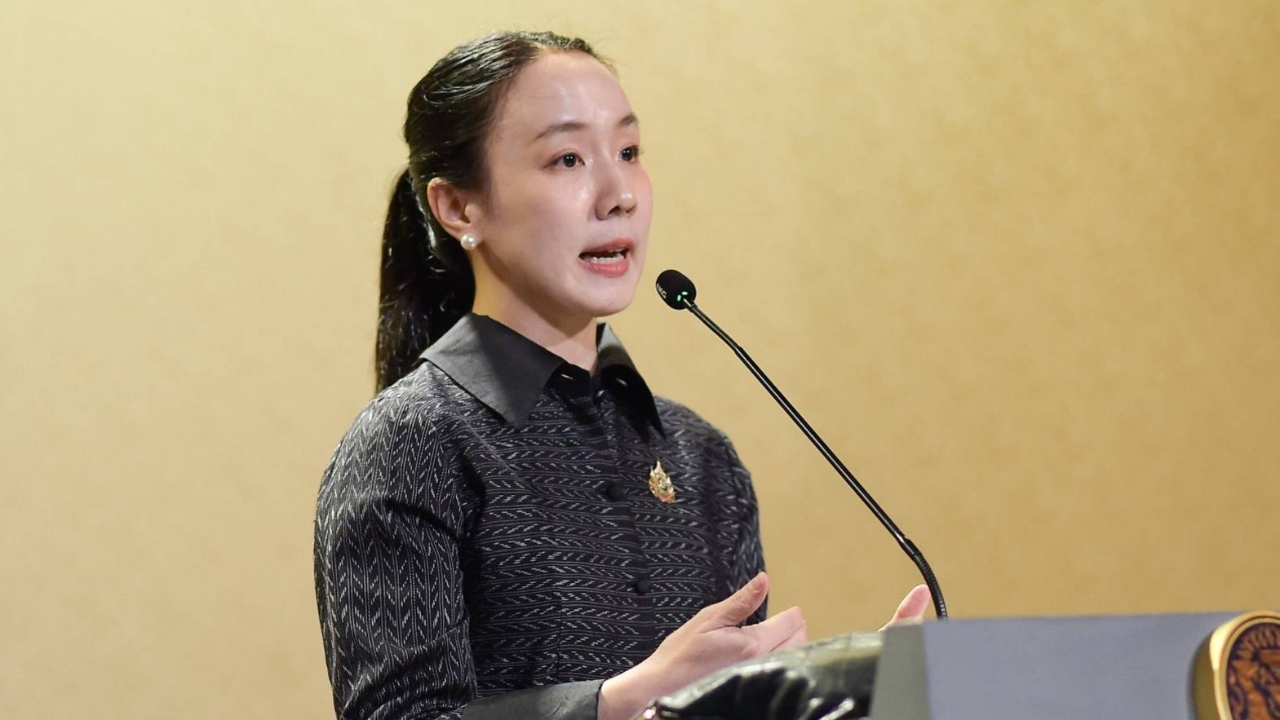
On 23 October 2026, Ms. Lalida Pertwivatana, Deputy Spokesperson for the Office of the Prime Minister, revealed that the government is advancing a new investment promotion tool to enhance competitiveness and attract foreign investment in line with international tax rules. The Revenue Department of the Ministry of Finance is currently seeking public feedback on the draft act concerning Qualified Refundable Tax Credits (QRTC) from 6 October to 5 November 2026 to gather input from businesses and the public before proceeding with legal steps.
Ms. Lalida explained that developing the QRTC tool aims to maintain Thailand’s investment competitiveness amid changing global tax regulations, especially regarding taxation of large multinational corporations, which may reduce the effectiveness of traditional tax incentives. The government prioritizes developing benefits that meet investor needs while ensuring clear, transparent criteria that consider impacts on state revenue.
QRTC is a tax credit model aligned with the Organisation for Economic Co-operation and Development (OECD) guidelines. Eligible recipients can use credits to pay taxes and may request cash or cash-equivalent refunds under specified conditions. However, not all businesses will automatically qualify or receive immediate cash refunds, as eligibility and approval processes under the law must be met.
Ms. Lalida described that the draft law proposes defining eligibility, types of eligible expenses or activities, and tax credit rates and values through royal decrees. Businesses wishing to use the benefit must submit applications with documentation to the Revenue Department, which will be reviewed by a Benefits Approval Committee chaired by the Revenue Department Director-General and including representatives from relevant agencies and experts to ensure approvals meet objectives and are verifiable.
Regarding usage, the draft law specifies that electronic benefit certificates are valid for four years from the committee’s approval date. Recipients can use credits to pay taxes per defined rules, and after three years from the benefit start date, may apply for cash refunds of remaining credit balances under set conditions. Receiving tax credit approval does not guarantee immediate cash payment.
To maintain fiscal discipline and protect state revenue, the draft law proposes a ceiling limiting the allocation of corporate income tax collected—after withholding tax payments reported on form Phor Ngor Dor 53—to no more than 1%. This cap serves as a funding source for benefits and administration. The committee will set annual benefit limits. The 1% cap is a proposed maximum allocation, not the tax credit rate each business receives.
Ms. Lalida added that the draft law includes mechanisms to prevent misuse, allowing the committee to modify or revoke benefits if recipients lose eligibility, fail to meet conditions, or do not cooperate with audits. It also allows recovery of used tax credits or cash received with interest according to rules, and prescribes penalties for false information or fraud to obtain benefits.
“The government aims to create an investment promotion tool aligned with global economic rules to maintain competitiveness and enhance opportunities to attract investment to Thailand. However, benefits must be transparent, verifiable, and fiscally controlled without creating uncontrolled burdens. Therefore, eligibility criteria, approval procedures, and recovery measures must be clearly defined,” Ms. Lalida said.
The Deputy Spokesperson concluded by inviting businesses, companies, juristic partnerships both Thai and foreign, private sector organizations, and the general public to submit opinions on the QRTC draft law principles via the Revenue Department website by 5 November 2026. Feedback is especially sought on eligibility, approval procedures, tax credit use, cash refund requests, and oversight mechanisms to ensure comprehensive development of investment promotion measures. At present, QRTC remains in the consultation phase and is not yet available for businesses to apply for or receive refunds.