

A proposal to the Student Loan Fund (กยศ.) aims to make the criteria more comprehensive and prepare strict rules to blacklist intentional defaulters in the credit bureau, fostering repayment awareness to reduce the Fund's liquidity shortage.
On 3 Sep 2026, Mr. Plathip Pimsuwan, a first-year student at Uttaradit Rajabhat University, together with a student group, attended a meeting to discuss the management of the Student Loan Fund (กยศ.) as affected parties, providing information and opinions. The meeting included the Education Committee and related agencies, including representatives from the Student Loan Fund, held at the Parliament Building.
The participating agencies agreed to propose extending tuition payment deadlines while awaiting appropriate criteria adjustments by the Student Loan Fund. They recommended addressing the 200 billion baht bad debt issue by blacklisting intentional defaulters through credit bureau records. Students called on the government to increase funding to meet loan demand.

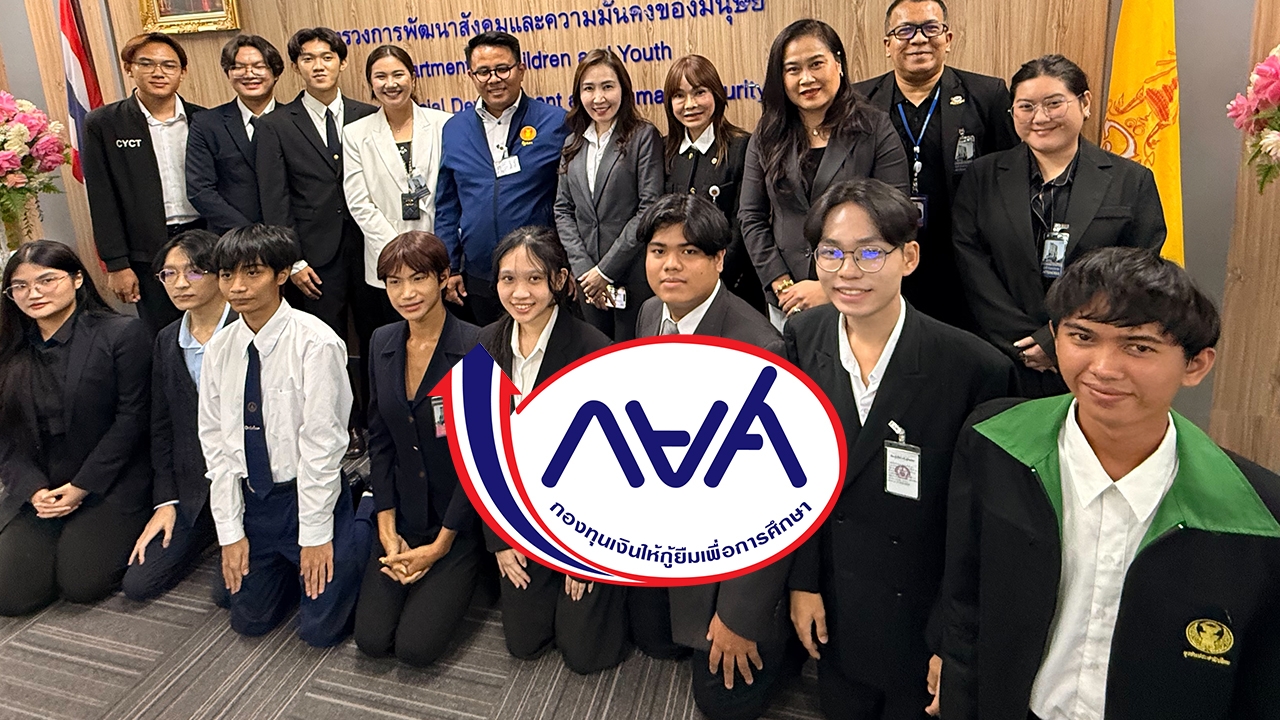
On 11 Sep 2026, the Child and Youth Council invited Mr. Teerasak Jiratarachu, Deputy Chairman of the Education Committee, to chair a meeting with related agencies including the Student Loan Fund, Budget Bureau, and university networks such as the Council of Rajabhat University Presidents of Thailand and the Council of Rajamangala University of Technology Presidents. The meeting was held at the Ministry of Social Development and Human Security to discuss solutions for many students at risk of dropping out due to unpaid tuition and to consider fair and humane adjustments to the loan criteria. The meeting took place in the Darunvithi Conference Room, 11th floor, Zone B, Ministry of Social Development building.
The meeting aimed to discuss preventive and supportive measures for students at high risk of dropping out of the education system. Related agencies deliberated on actionable scopes and proposed an operational plan within a two-month timeframe.

Mr. Plathip revealed that about 20,000 students did not receive loan quota allocations, while approximately 16% of all applicants received quotas allocated by the Student Loan Fund to over 20 educational institutions nationwide.
For example, at each university, such as Naresuan University, which was allocated 1,300 quotas but had 2,900 applicants, with roughly 50% not receiving quotas across tiers 3 and 4. Srinakharinwirot University had 2,200 applicants but only 670 quotas allocated, with over 50% not receiving allocations.
A representative from the Student Loan Fund said the main problem is that some graduates remain unemployed, preventing the Fund from collecting repayments to maintain liquidity. They are seeking ways to ensure graduates find employment, aligning with the Fund's philosophy to support underprivileged students by providing educational opportunities. With employment and income, borrowers can repay the Fund, improving quality of life.
In fields where graduates exceed labor market demand, the Fund encourages new students to shift toward sectors with actual job needs by setting new criteria. This has caused misunderstandings among applicants who believe any field qualifies for loans. The Fund prioritizes support for fields crucial to national needs, reducing allocations for other fields. This mechanism aims to align students with labor market demands, fulfilling the Fund’s role in developing human resources for future labor needs.

Allocation of loan quotas by tiers at the Student Loan Fund.
Tier 1 (Critical shortage fields for the country) accounts for 13% of borrowers.
Tier 2 (Above-income threshold but studying in shortage fields—tuition only) accounts for 1% of borrowers.
Tier 3 (General underprivileged borrowers) accounts for 52% of borrowers.
Tier 4 (Other underprivileged groups) accounts for 34% of borrowers.
Borrowers truly underprivileged (Tiers 3 and 4) remain the main group receiving a combined 86% (nearly 70-80%) of total loan allocations, not losing quotas to Tier 2 as feared.
Family income threshold is 360,000 baht per year.
The Student Loan Fund explained it raised the family income ceiling from around 200,000 baht to 360,000 baht per year (averaging combined parental income of no more than 30,000 baht per month) to allow families to deduct expenses. However, in practice, if income slightly exceeds the limit, applicants are disqualified under budget constraints to prioritize the most needy.
The Student Loan Fund stated it operates as a revolving fund relying mainly on repayments from previous borrowers but is facing severe liquidity issues, including:
Economic downturns have reduced parental incomes, increasing immediate loan demand from new and current students.
Repayment income has declined due to government relief measures and a new Student Loan Fund Act that lowered penalty interest (previously 7.5%) meant to encourage repayment discipline. As a result, borrowers prioritize other expenses over loan repayment.
Quantitative limitations arise because by law, the Fund must support borrowers until graduation (4 years). Currently, over 500,000 previous borrowers accumulate, consuming most budget to support them, leaving fewer quotas for new borrowers.
For cases where previous borrowers are suspended mid-term, the Fund uses income data linked with government agencies to identify those exceeding the 360,000 baht family income threshold and temporarily halts loan approvals. Appeals can be filed to unlock borrowing rights.
Mr. Teerasak, chairing the meeting, proposed a foreign model where students repay small amounts annually, e.g., 500 baht during study, to build repayment responsibility and reduce principal without interest. Using research data to identify fields with 100% employment post-graduation guides precise labor market targeting. Taxes paid by borrowers after employment would be used to reduce principal (e.g., 10% discount), incentivizing tax compliance and loan repayment. Loan contracts could be separated or packaged to borrow only tuition, only living expenses, or co-pay with parents, as data shows most budget losses occur in living expenses, not tuition.
Statistically, volunteer hour tracking does not correlate with future repayment motivation, so it was proposed to remove the Student Loan Fund's volunteer requirement and return promotion of activities to universities. The system of income certification by village chiefs or local officials has high error rates and political misuse risks; thus, the Fund should eliminate this mechanism and design more accurate income assessment tools.
A representative from the Rajabhat University Presidents Council stated that among 36 member universities, approximately 50-60% of students applying for loans have not received allocated funds, for example:
Nearly 4,000 students requested loans through the Pre-Approve system.
Only 1,319 were allocated quotas.
This accounts for about 30% of total demand, causing heavy complaints from parents and students who mistakenly believe the university is the lender. The family income ceiling of 360,000 baht per year creates difficulties for self-employed/trade families in providing proof and causes some truly needy students to fall out of the system. Universities can delay tuition collection but only to a limited extent, as they must ensure students receive loans; otherwise, tuition cannot be collected.
A representative from the Rajamangala University of Technology Presidents Council said universities currently act as "tax return analysts" without expertise in tax types (Forms 90, 91, 94), while most students and parents lack financial and tax knowledge. This results in requiring students to write essays explaining hardships for consideration.
A representative of the Child and Youth Council noted that universities have varied academic calendars and tuition payment conditions, causing inconsistent document submission periods. Many students are unaware of extended tuition payment measures due to insufficient communication. The Fund also lacks clear public statistical information for students to reference when claiming rights.
A representative from the Rajamangala University of Technology Presidents Council revealed that most universities allocate budgets to employ students, helping them repay Student Loan Fund debts promptly. They request the Fund to disclose repayment and default rates of alumni by university to allow institutions to plan assistance and awareness campaigns more effectively.

Student Loan Fund defaults are divided into two groups requiring different responses.
A representative from the Rajamangala University of Technology Presidents Council recommended distinguishing intentional defaulters—those with payment capacity (e.g., active credit cards, paying other debts) but deliberately avoiding repayment to the Fund.
Proposed government measures include strictly enforcing laws and social sanctions, such as banning defaulters from public service or collaborating with private sectors to deny employment rights, to establish responsibility standards.
The truly underprivileged group includes graduates who remain unemployed or have insufficient income for living expenses.
Proposed measures for this group involve government support and relief without punishment, using precise targeting to help them survive.
A representative from the Budget Bureau stated they will not allow the Student Loan Fund to face liquidity shortages. If urgent needs arise due to delayed repayments from previous borrowers, the Bureau is prepared to consider allocating "central funds" to subsidize and maintain the Fund's operational liquidity.
Although the Budget Bureau is ready to support with central funds, it expressed concern over the country’s overall budget burden. It recommended that the Student Loan Fund urgently improve debt collection management efficiency to restore revolving funds for approving new loans.