

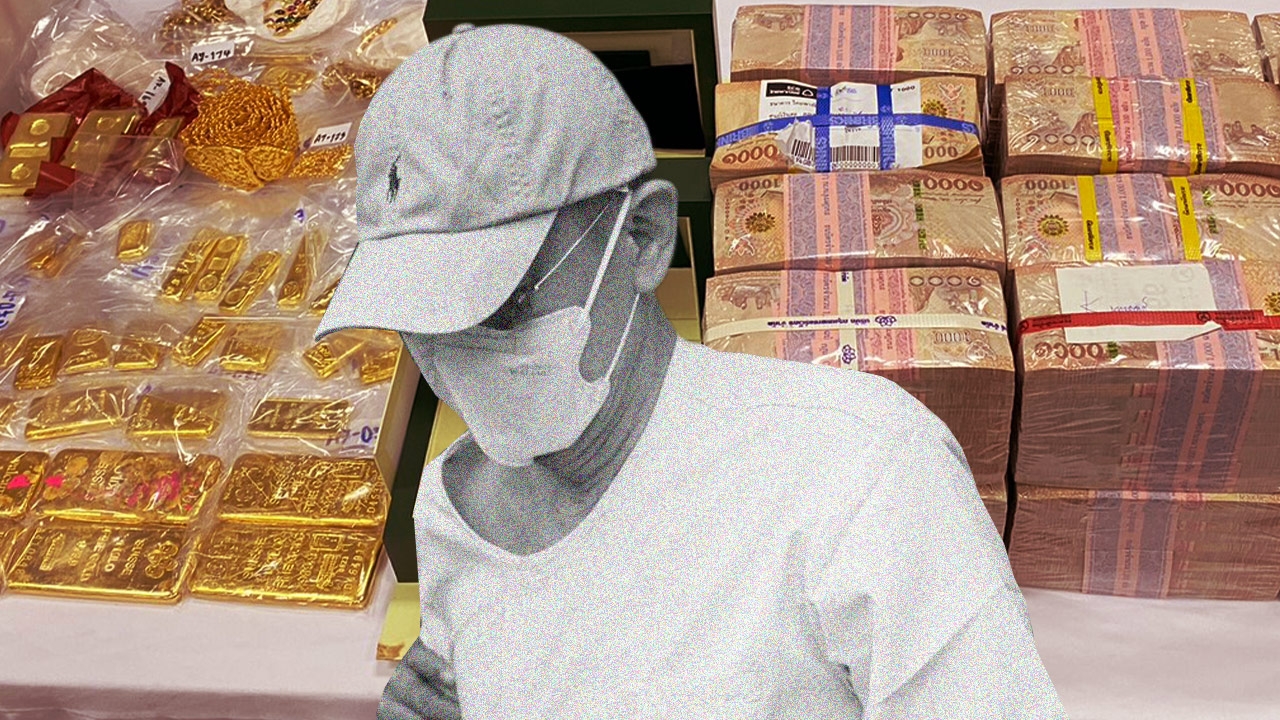
The Hwan Chot Foundation controversy unpacks the flow of 10 million baht—identifying which funds truly assist temples and which are misappropriated. “Maha Mee” scrutinizes the structure of vested interests, stresses that collaborations producing sacred amulets must be transparent, and insists that every baht from amulet sales must be deposited into the temple’s official account first.
Following the arrest of former abbot Luang Pho Chot of Phutthaisawan Temple and layperson Sika Ae for embezzling temple funds, police successfully apprehended them.
On 20 Sep 2026 GMT+7, Pol. Maj. Gen. Phatthanasak Bupphasuwan, Commander of the Crime Suppression Division, revealed that after obtaining financial transaction data from Phutthaisawan Temple, investigators forwarded all financial documents to the Anti-Money Laundering Office (AMLO) for review to determine involved parties. AMLO has already returned partial findings, and the investigation team is currently examining these data.
Reports indicate that after Mr. Atichot was arrested and his conduct scrutinized, it was found he had established the Hwan Chot Foundation, appointing himself chairman with a total of six board members. So far, five have been questioned by investigators, providing useful information to the case. The last board member identified was Mr. Samer Nguangam, also known as “Pong Suphan,” a renowned amulet expert. Initial inquiries show no connection between Pong Suphan and the alleged corruption.

Thai Rath Online’s special task force consulted “Maha Mee” (Dr. Prayut Prathetsena), Vice Chairman of the Thana Army Lawyers Foundation and a legal expert on the Tipitaka. He believes repeated offenses are possible due to longstanding lax management of temple finances. The core issue stems from the abbot’s authority under Section 31 of the Sangha Act, which grants him company-like powers to manage all temple affairs. Unlike private companies, temples lack state supervision, taxation, or mandatory annual asset declarations.
Although the 2021 Ministerial Regulations on Temple Asset Management require financial reporting, they impose no clear penalties for non-compliance. Since temples are nonprofit entities exempt from taxes, this legal gap means rules exist only on paper. Violations are hard to detect and punish, allowing embezzlement of temple or donated funds to persist unnoticed for 10 to 30 years. Existing laws are insufficient to deter or prevent this.
Regarding vested interests and partnerships with outsiders such as amulet experts, for example, producing 100,000 amulets generating 10 to 20 million baht, financial trails can be traced. Temple disbursements must be approved by the abbot, treasurer, and temple committee with clear timelines. Ministerial Regulations from 1968 and 2021 require all temple funds to be deposited first into the temple’s account before disbursement for authorized uses.
He categorized amulet experts into two groups:
First, transparent collaborations that genuinely help produce amulets and generate income for the temple, with clear agreements on investment and expense deductions, ensuring every baht is fully deposited into the temple’s accounts.
Second, collaborations where outsiders benefit more than the temple, funds bypass the temple’s accounts and go into private pockets. In such cases, the abbot, treasurer, or some committee members collude to divert large sums, constituting corruption.
Maha Mee warned that those with goodwill wanting to help temples can do so lawfully, but must not divert income away from the temple. If a temple’s name guarantees authenticity, all funds must enter the temple’s account first and cannot be distributed arbitrarily.

Regarding enforcement and penalties, Maha Mee explained that legal punishments do exist, such as Section 157 of the Criminal Code. Since monks and treasurers are considered officials under the law, misconduct or dereliction of duty can lead to arrest. However, this addresses symptoms rather than causes. The root problem lies in legal loopholes within the Sangha Act and ministerial regulations granting excessive authority to certain individuals and the lack of a central body to rigorously audit temple finances. These issues require multiple legal reforms.

Another key issue is foundation establishment. Temples are special legal entities under public law per the Sangha Act, whereas foundations or associations are private legal entities under civil and commercial law, organized for charitable purposes and managed by a board chairman.
Setting up a foundation to support temple activities is not illegal. The problem arises when temples create foundations managed by the abbot himself, effectively outsourcing temple management—handling funds and operations in the temple’s name. This facilitates money moving between accounts inappropriately, which is unlawful and must be clearly distinguished.